
Categories
real estatePublished September 9, 2026
How Much Do You Need To Buy a Home in San Antonio in September 2026?
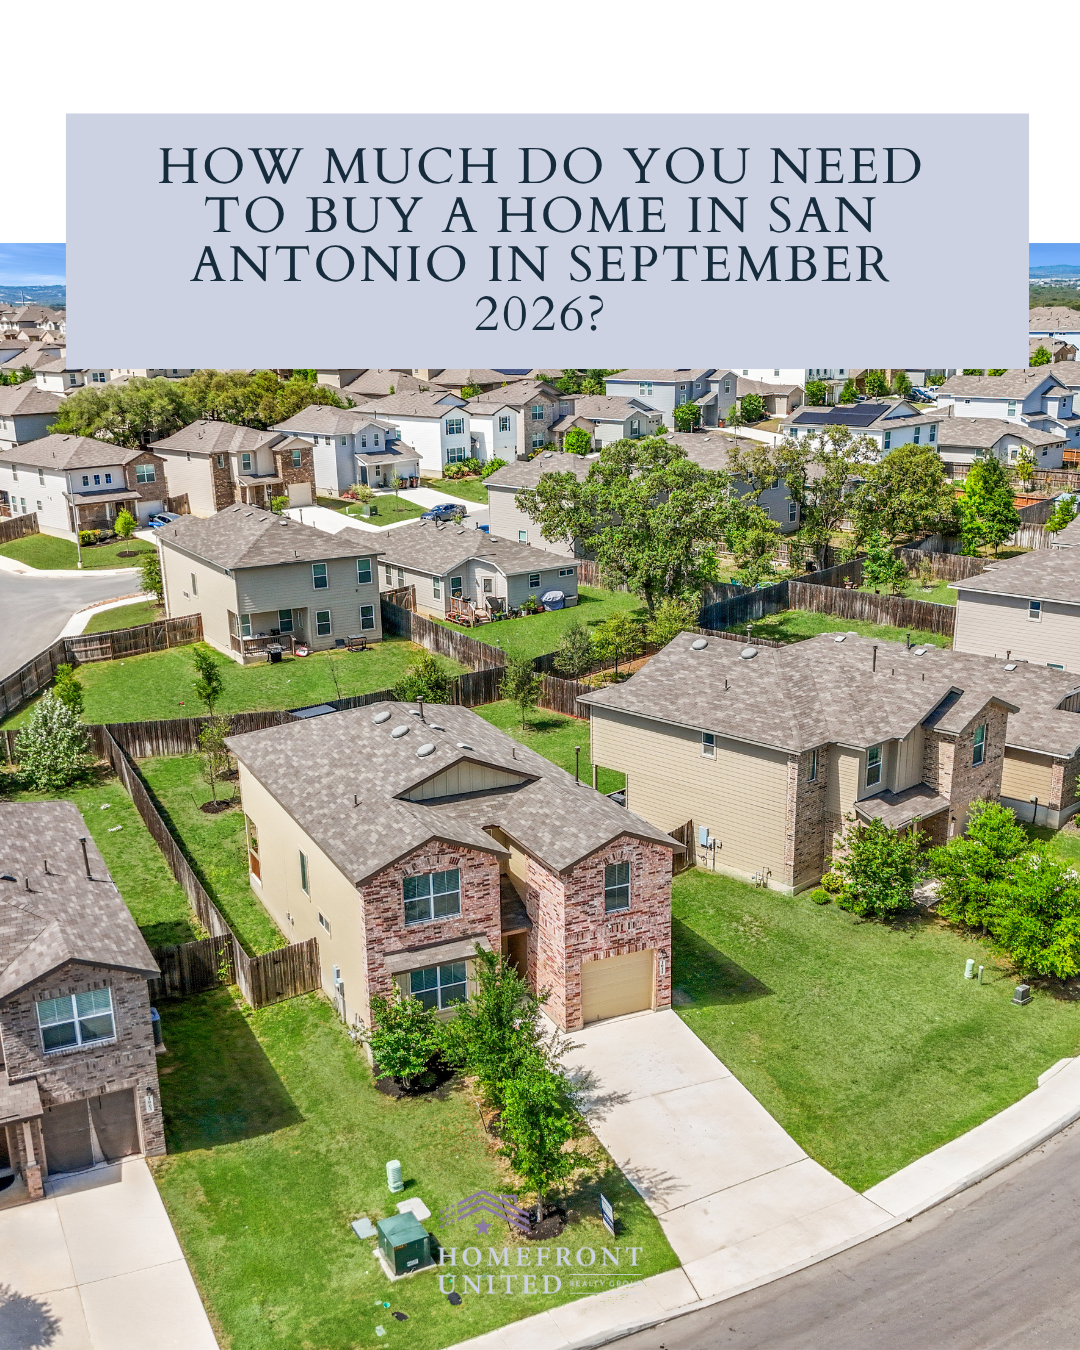
How Much Do You Need To Buy a Home in San Antonio in September 2026?
Thinking about buying a home in San Antonio this September? One of the first questions most buyers ask is:
“How much money do I actually need to buy a home?”
The answer depends on the home's price, your loan type, credit profile, negotiated terms and whether the seller contributes toward closing costs.
The good news? You don't necessarily need a huge amount of cash saved to become a homeowner.
San Antonio remains one of the more affordable major Texas housing markets. Recent market data puts the city's median sale price around the mid-$200,000s to low-$300,000s, depending on the source and reporting period. Redfin reported a median San Antonio sale price of approximately $265,000 for the three months ending June 2026, while July data reported by Redfin showed a median sale price of $320,243.
Here's what prospective buyers should know about the costs of purchasing a home in September 2026.
The Big Three Costs to Plan For
When budgeting for a home purchase, think about three major categories:
- Down payment
- Closing costs
- Cash reserves and other upfront expenses
Your exact amount will depend on your financing.
How Much Is a Down Payment?
The down payment is the portion of the purchase price you pay upfront rather than financing through your mortgage.
Here's an example using a $300,000 home:
| Down Payment | Amount |
|---|---|
| 0% | $0 |
| 3% | $9,000 |
| 3.5% | $10,500 |
| 5% | $15,000 |
| 10% | $30,000 |
| 20% | $60,000 |
These numbers are examples only. Loan programs have different eligibility requirements, and some buyers may qualify for assistance programs or seller contributions that reduce the amount of cash needed at closing.
VA Loans Can Be a Major Advantage for Eligible Buyers
For eligible veterans and active-duty service members, a VA loan can make buying a San Antonio home considerably more accessible.
A VA loan can allow qualified borrowers to purchase with 0% down, subject to program requirements and the borrower's financial qualifications.
That means a buyer purchasing a $300,000 home could potentially avoid a $15,000, $30,000 or $60,000 down payment required under some conventional scenarios.
However, 0% down does not necessarily mean $0 needed at closing.
Buyers may still have closing costs, prepaid expenses, inspections, appraisal costs and other transaction-related expenses.
For San Antonio's large military community, this makes understanding VA financing particularly important.
What About First-Time Buyers?
First-time buyers often assume they need 20% down to purchase a home.
That's not necessarily the case.
Depending on the loan program, qualified buyers may be able to purchase with a down payment as low as 3% to 3.5%.
For example, on a $300,000 home:
3% down = $9,000
3.5% down = $10,500
That's significantly less than a 20% down payment of $60,000.
The trade-off is that lower-down-payment loans can come with additional costs, such as mortgage insurance, depending on the loan type.
A lender can compare different financing options based on your income, credit, debts and goals.
Don't Forget Closing Costs
One of the biggest mistakes first-time buyers make is saving for the down payment but forgetting about closing costs.
Closing costs can include expenses such as:
- Loan origination and lender fees
- Title services
- Appraisal
- Recording fees
- Prepaid property taxes
- Homeowners insurance
- Prepaid interest
- Escrow funding
- Other transaction expenses
The exact amount varies significantly from one transaction to another.
That's why it's important to ask your lender for a Loan Estimate early in the process so you have a better idea of how much cash you'll need.
Can the Seller Help With Closing Costs?
Sometimes.
Depending on the property, market conditions and loan guidelines, buyers may be able to negotiate for the seller to contribute toward certain closing costs or other allowable expenses.
This can be especially relevant in a market where buyers have more choices and negotiating leverage.
San Antonio currently has elevated inventory compared with recent years. Zillow reported 8,465 homes for sale in July 2026, while Realtor.com reported 14,217 active listings across the broader San Antonio-New Braunfels market. Realtor.com also reported that San Antonio's active listings were up 4.7% year over year.
That doesn't guarantee that every seller will agree to concessions, but it can give qualified buyers more opportunities to negotiate.
How Much Should You Have Saved?
Instead of asking only, “How much is the down payment?”, consider building a complete home-buying fund.
For example, a buyer purchasing a $300,000 home might need money for:
Down payment:
$9,000–$60,000 depending on the loan
Closing costs:
Varies by loan, transaction and negotiated terms
Inspection:
Budget for a professional home inspection and potentially additional inspections when appropriate.
Appraisal:
Often required by the lender, depending on the loan.
Earnest money:
An upfront deposit that may be credited toward the purchase at closing.
Option fee:
For applicable Texas transactions, this may be negotiated as part of the contract.
Moving expenses:
Don't forget the cost of actually getting into your new home.
Emergency savings:
It's wise not to drain your entire savings account just to close.
What If You Have $10,000 Saved?
You may still have options.
For example, if you're considering a $300,000 home and qualify for a 3% down conventional loan, the down payment would be approximately $9,000.
But that doesn't mean you should spend every dollar you have on the down payment.
Your lender and real estate professional can help you determine whether your available cash is enough after accounting for closing costs and reserves.
Depending on your loan program and the negotiated transaction, assistance programs, seller contributions or other strategies may also help reduce the amount of cash you need to bring to closing.
What Does a $300,000 San Antonio Home Look Like?
A $300,000 purchase price is useful as an example, but remember that San Antonio's housing market varies significantly by neighborhood.
Recent market data shows that homes can sell above or below the citywide median depending on location, size, condition and other factors. Zillow reported a June 2026 median sale price of $287,667 and a July median list price of $291,567.
That means buyers shouldn't assume that a citywide number tells the whole story.
A $300,000 budget may look very different in:
- Northwest San Antonio
- Northeast San Antonio
- Southwest San Antonio
- Stone Oak
- Alamo Heights
- Schertz
- Cibolo
- Converse
- Universal City
- New Braunfels
The best approach is to identify the neighborhoods that fit your lifestyle and commute, then look at current inventory within your actual budget.
Don't Forget the Monthly Payment
Having enough money to close is only one part of the equation.
You also need to be comfortable with the ongoing monthly cost of owning the home.
Your payment may include:
Principal + Interest + Property Taxes + Homeowners Insurance + HOA Fees
Mortgage rates remain an important affordability factor in 2026, and even a small change in interest rate can significantly affect a buyer's monthly payment.
That's why it's important to shop based on monthly affordability, not just purchase price.
Is September 2026 a Good Time to Buy?
There isn't one perfect month for everyone, but the current San Antonio market offers buyers some advantages.
Inventory has increased, home values have moderated, and buyers have more opportunities to negotiate than they did during the highly competitive housing market of the early 2020s.
Zillow's July data showed that 57.8% of sales closed below the listing price, while the median sale-to-list ratio was 98.8%.
That can create opportunities for buyers who are prepared and understand how to evaluate a property.
However, buyers shouldn't wait for the market to reach a hypothetical “perfect” point. The right time to buy depends on your finances, employment situation, long-term plans and ability to comfortably afford the home.
A Simple September 2026 Home-Buying Checklist
Before you start touring homes, consider these steps:
1. Check Your Credit
Your credit profile can affect the loan programs and interest rates available to you.
2. Talk to a Lender
Get pre-approved so you understand your potential purchasing power.
3. Determine Your Cash Available
Look beyond your down payment and account for closing costs, inspections, moving expenses and reserves.
4. Choose a Comfortable Monthly Payment
Don't automatically shop at the maximum amount a lender approves.
5. Research Neighborhoods
Consider commute times, schools, amenities, taxes, HOA fees and future plans.
6. Explore Loan Options
Compare conventional, FHA, VA and other financing options for which you may qualify.
7. Look at Current Inventory
With more homes available in San Antonio, you may have more opportunities to compare properties and negotiate terms.
So, How Much Do You Really Need?
There isn't one magic number.
A buyer purchasing a $300,000 San Antonio home could potentially need:
$0 down with an eligible 0%-down loan such as VA financing,
around $9,000 with a 3% down payment,
around $10,500 with a 3.5% down payment,
or $60,000 with a 20% down payment.
But the down payment is only part of the picture.
Your actual cash requirement depends on your financing, closing costs, prepaid expenses, negotiated seller contributions, assistance programs and individual financial circumstances.
Ready to See What You Can Afford?
If you're thinking about buying a home in San Antonio this September, start with your actual numbers—not a generic online calculator.
A lender can help you understand your financing options and estimated cash-to-close, while a local real estate professional can help you identify neighborhoods and homes that fit your budget.
Thinking about buying in San Antonio?
The Homefront United Realty Group team is here to help you understand the local market, explore your options and make informed decisions throughout your home-buying journey.
This article is for general informational purposes only and is not financial, tax, mortgage or legal advice. Loan programs, rates, fees, eligibility requirements and closing costs vary. Speak with a qualified lender for personalized financing information.
Find homes in San Antonio here
Home is where the heart is. Let us help you on your search for peace and comfort in your own home.
Search for Homes
Get Your Free Ultimate Guide to Living in San Antonio
Karina Gafford
Broker Associate | Homefront United Realty Group | KW City View
or another way